


The rule in one division
A consistency rule limits how much of your total profit may come from a single day, or occasionally a single trade. You are compliant when:
best single day ÷ total profit ≤ the cap
That is the whole rule. A trader with $10,000 of profit, $4,500 of it from one Tuesday, is at 45% against a 30% cap. The payout is held. Not because a loss limit was breached, not because any trade broke a rule, but because the shape of the profit is wrong.
It is the rule that most often turns a successful funded account into a dispute, and the one least likely to be understood before it bites.
What it looks like on a live account
Most firms check this quietly at payout and show you nothing in the meantime. A few now put the calculation on the dashboard, which is the clearest way to see what it actually measures.
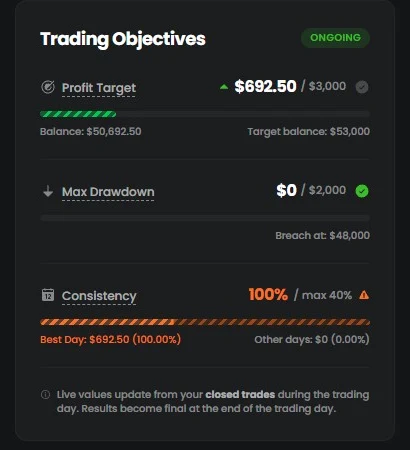
Two things on that panel are worth taking away.
First, the rule is spelled out as an arithmetic: Best Day $692.50 (100.00%) against Other days $0 (0.00%). Whatever a firm's terms say in words, this is the sum being done.
Second, 100% on day one is not a problem. One profitable day into an account, your best day is by definition all of your profit, so the figure starts at its worst possible reading and falls as trading days accumulate. It is arithmetic, not a breach. Knowing that in advance saves a support ticket.
Two months, the same profit, opposite outcomes
This is the part that makes the rule click. Both accounts below made exactly $3,560 across twelve trading days. One qualifies for a payout and one does not.
The second trader is not better. They may well be worse, since the first one found a $1,900 day. The rule does not measure how much you made or how skilfully you made it. It measures whether any one session carried the month.
You can run your own numbers through the same calculation in the consistency rule calculator, including the losing days, which is where most mental arithmetic goes wrong.
The arithmetic for staying inside one
Let B be your best single day's profit, T your total profit, and c the cap as a decimal. You are compliant when B / T ≤ c.
Rearranged, the total profit you need before a given best day stops being a problem is T ≥ B / c.
Worked on the concentrated month above: best day $1,900, cap 40%. You need a total of at least $1,900 ÷ 0.40 = $4,750. The total is $3,560, so another $1,190 has to come in before a single dollar can be withdrawn. Every losing day in the meantime pushes that number up rather than down.
Why your next good day can make it worse
Here is the part that surprises people, and the reason the rule feels like a moving target.
The cap is a share of a total that your next winning day also increases. So a day smaller than your current best improves the ratio, and a day larger than your current best becomes the new numerator and raises the requirement with it. Starting from best day $1,900, total $3,560, cap 40%:
| Next day | New total | New best day | Best as % of total | Result |
|---|---|---|---|---|
| +$400 | $3,960 | $1,900 | 48.0% | Still held, but closer |
| +$1,190 | $4,750 | $1,900 | 40.0% | Clears, exactly |
| +$2,373 | $5,933 | $2,373 | 40.0% | Clears, exactly |
| +$2,500 | $6,060 | $2,500 | 41.3% | Held again, and by more |
| +$5,000 | $8,560 | $5,000 | 58.4% | Much further away than before |
Read the last row twice. The trader made $5,000 in a day and went backwards. There is a window, here between $1,190 and $2,373, in which one more session settles it, and above that window every extra dollar of profit costs you.
So a big winning day is a reason to delay a payout request, not to accelerate one. The instinct after an outstanding session is to lock the money in, and that instinct is precisely what triggers the hold, because the ratio is at its worst immediately after the day that caused it.
Why trading smaller does not fix it
The natural response is to trade smaller so no single day dominates. It does not work, and seeing why is what makes the rule finally make sense.
Halve every position and you halve the best day and halve the total. $950 out of $1,780 is still 53%. The ratio is scale-invariant: it cannot be solved by trading smaller, only by trading more evenly.
What actually satisfies it is more trading days with a result. That is why the rule quietly selects for a particular kind of trader. It is not a difficulty setting, it is a style filter, and knowing which side of the filter you are on is a purchase decision rather than a trading one.
Why firms impose it
The intent is defensible, and worth understanding rather than dismissing.
A firm deciding whether to keep funding you is trying to distinguish a trader with a repeatable edge from someone who put everything on one number and was right. Both look identical on a profit-and-loss statement. A distribution requirement separates them: an edge produces profit across many sessions, luck produces it in one.
There is a second, less-discussed reason. Firms hedge selectively, as covered in is prop trading legitimate. A trader whose profit arrives in one unhedged spike is a real loss to the firm in a way that steady profit is not.
Neither reason makes the rule harmless to you. But it does mean a firm with a published, reasonable consistency rule is behaving rationally rather than looking for an excuse.
Why it usually bites so late
The dashboard above is the exception. At most firms a consistency rule is not enforced by the platform at all: nothing stops you making 60% of your monthly profit on Tuesday, no warning appears, and no meter moves.
You find out when you request a payout and the review declines it, or asks you to keep trading until the distribution evens out.
That timing is what makes it dangerous. By the time it applies you have already done the work, and money you thought you had earned is contingent on trading you have not yet done. This is the defining characteristic of a soft rule: the platform stops you from breaching hard limits, so the rules you must actively police yourself are precisely the ones nobody is enforcing in real time.
Published versus unpublished, which matters more than the number
A published rule such as "no single day may exceed 25% of total profit" is a constraint. You can calculate against it, plan around it, and know with certainty whether you comply. It is demanding but it is honest.
An unpublished rule such as "we expect consistent trading behaviour" cannot be planned around. It is evaluated after the fact, by a person, against a standard you were never given. There is no calculation you can do and no way to demonstrate compliance in advance.
An unquantified consistency requirement is worse than a strict published one. A 20% cap you can see is more workable than an undisclosed cap that might be 20%, might be 40%, and might depend on who reviews your account.
When we document a firm, an unquantified consistency requirement is recorded as unquantified and flagged as a risk on the profile rather than treated as a neutral field. It is the single most reliable warning sign in this industry, and it runs through prop firm scams and how to spot them.
The variants
Not all consistency rules are the daily kind, and they are not equally survivable.
| Variant | What it caps | Who it hurts |
|---|---|---|
| Per-day | One session's share of total profit | Event traders, anyone with a lumpy calendar |
| Per-trade | One trade's share of total profit | Anyone who lets winners run, even on an even month |
| Position size | Largest position against your average | Volatility-based sizing, which varies size by design |
| Minimum profitable days | Nothing directly, requires spread instead | Low-frequency strategies |
| Applied in the evaluation | The same ratio, before funding | Anyone who builds a lead in one session |
The position-size variant is the one people breach by accident, because a wide-stop trade legitimately takes a smaller position and a tight-stop trade a larger one. Check for it specifically if you size by volatility.
Rules that do the same job under another name
A firm can advertise "no consistency rule" and still constrain the same behaviour. Look for:
- A minimum number of profitable days before a payout.
- A cap on position size relative to account size.
- A minimum hold time, which limits how much a single fast move can contribute.
- A broad "abusive or manipulative trading" clause, covered in prohibited strategies.
The absence of the named rule is not the absence of the constraint. Read the payout section in full rather than searching for the word "consistency".
Who this structurally excludes, and what to do about it
For some strategies a consistency rule is not an inconvenience, it is incompatible. News and event traders concentrate returns around scheduled releases by design. Low-frequency breakout traders take many small losses and a few large wins, which is the shape of the edge rather than a flaw in it. Swing traders may have four results in a month, one of which is necessarily the biggest.
Conversely, high-frequency intraday strategies with a consistent win size satisfy these rules almost automatically and can largely ignore them.
If you are in the first group, this field belongs above the drawdown structure in your selection criteria, which is unusual. The options, in order of sensibility:
- Choose a firm without the rule, and verify it in the funded agreement rather than the marketing page. Firms with no consistency rule covers what to check, and the comparison filters on the documented field.
- Choose a longer payout cycle, which gives more days for the distribution to even out. A 30-day cycle is friendlier to a lumpy strategy than a 14-day one, despite feeling slower.
- Split across two accounts at different firms, so one outsized day does not dominate one book, bearing in mind that most firms prohibit mirroring the same trades across accounts.
- Trade a second, higher-frequency method purely to populate the distribution. This is the option that looks clever and most often costs money, because you are now trading a strategy chosen for its shape rather than its edge.
A consistency rule makes some perfectly good traders a bad fit for some perfectly good firms. That is a matching problem, not a moral one, and it is cheaper to solve before the fee than after the payout is refused.
Trading deliberately inside one
If you have chosen a firm with a published cap, four habits make it a non-issue.
Track the ratio continuously, not at payout time. One column in your journal: best day, total, and the resulting percentage. See journaling during an evaluation.
Consider scaling out on exceptional days. A position closed in three parts across three sessions books three days of profit instead of one. The total is identical, the distribution is not, and the distribution is what the review measures. Two cautions: check whether your firm books the day by close time, since a position opened Monday and closed Thursday books its whole result on Thursday at most firms; and do not let an accounting rule reshape a strategy that works. If scaling out costs more in expectancy than the delayed payout costs in patience, take the delay.
Do not chase a big day with a bigger one. The table above is why.
Time requests to the distribution, not to the calendar or to how much you want the money.
Consistency and the drawdown pull in opposite directions
The two rules that decide most funded outcomes ask for opposite behaviour, and firms rarely mention that they interact.
A trailing drawdown punishes giving profit back, which pushes you toward taking gains quickly and keeping days small. A consistency rule punishes concentration, which pushes you toward more days with results. So far they agree. Where they collide is at the end of a payout window: the trader who is $1,190 short of an even distribution is being asked to keep trading, on an account whose drawdown has already tightened around a high-water mark, purely to satisfy a ratio.
That is the situation in which funded accounts are most often lost. Not in a bad month, but in the extra week of trading that a good month required. If you find yourself opening positions whose only purpose is to move a percentage, the right answer is almost always to take the smaller payout later, and to size against the drawdown as though the ratio did not exist.
What to ask before you buy
Four questions, in writing, and keep the reply. A firm that answers all four in specific numbers has a consistency rule you can trade under. A firm that answers in adjectives has one you cannot plan for.
- Is the cap measured on the best day or the best trade, and what is the exact percentage? The two produce very different sizing.
- Is it applied during the evaluation, on the funded account, or only at payout review? This decides when it can hurt you.
- Is the window the payout cycle, the account's whole life, or a rolling period? A rule measured over the account's life never resets, so an early outsized day follows you for months.
- If the distribution fails, is the payout deferred or forfeited, and does the account stay open? Deferred is an inconvenience. Forfeited is a different product.
The exercise is diagnostic in itself. The response time and the precision of the answer tell you more about a firm than any review score.
If a review raises it
Ask for the specific number being applied and where it is published. If the firm supplies both, you have a factual conversation and can calculate exactly how much further you need to trade.
If the firm cannot point to a published threshold, say so in writing and ask what standard is being applied. That request is reasonable, and the answer, or the absence of one, tells you whether to keep the account. Keep the correspondence either way, and see what to do if a payout is delayed for the escalation path.
Where to go next
Run your own numbers: the consistency rule calculator. What else the payout review examines: the consistency review at payout. The full payout process: how prop firm payouts work. And the broader class of rules that are checked rather than enforced: what counts as a breach.